The infinite banking concept is a strategy that uses a specially designed whole life insurance policy as a personal capital base you borrow against, so the policy keeps compounding while the borrowed dollars work elsewhere. Nelson Nash coined it. The discipline behind it is what determines whether it creates value.
The mechanics of infinite banking are largely correct, and the framing is where people lose money. The strategy is real. The version that promises tax-free growth, guaranteed returns, and money that works in two places with no constraint is a marketing simplification, and treating it as the whole picture is how entrepreneurs end up with an expensive policy doing nothing for them.
Our own short animated explainer shows why the simple version is so persuasive. Income comes in, you run it through a "family bank" you own and control, and the same dollar grows, stays liquid, and gets deployed into opportunities. Drawn out on a whiteboard, it looks like there is no tradeoff anywhere.
At BetterWealth, we have structured more than 2,000 policies across all 50 states. We respect the simple explainers, and we watch what happens when people act on them without the discipline layer. What follows is the rest: where the language needs tightening, the math that decides whether borrowing makes sense, and the framework we call The And Asset that turns the concept into a working life insurance strategy.
- Infinite banking uses a specially designed whole life policy as a capital base you borrow against, not a savings account.
- You are not borrowing from yourself: the loan comes from the carrier and is collateralized by your cash value.
- Cash value grows tax-deferred and compounds net of mortality and expense charges, not at the headline dividend rate.
- For a healthy individual, a well-designed policy does not break even in year one or two; cash value crosses contributions around year five.
- The And Asset rule: only borrow when the deployed return clears the carrier's loan cost. Otherwise, do not borrow.
- This is for entrepreneurs and value creators who deploy capital, not for early-stage savers or debt fixes.
The animation walks the whole concept visually, from income flowing into the family bank to the mortgage-style loan mechanism. Watch it for the picture, then read on for the math and the discipline a short video has no room for:
01 / The problemWhat problem is infinite banking actually solving?
Infinite banking addresses a structural leak that conventional financial advice ignores: you lose money either by paying interest to outside lenders, or by leaving capital idle and absorbing the opportunity cost. Most people experience both at once. They finance cars, homes, and businesses through banks, and they park reserves in accounts earning almost nothing while good opportunities pass by because the cash was not available at the right moment.
Nelson Nash framed this as the cost of giving up the banking function in your own life. Every dollar that flows through your hands either builds your capital base or someone else's. The sharp question is this: what if, before you save, spend, or invest, you first ran that money through a place you own and control?
Money only does two things. It gets saved or it gets consumed. The question is who controls the banking function in between, you or someone else.
02 / The frameworkWhat is infinite banking, and what does the concept actually mean?
The infinite banking concept means using a specially designed whole life policy as a capital base you borrow against, while the policy keeps compounding. That is the mechanical definition popularized by Nelson Nash in Becoming Your Own Banker. The "family bank" is a clean metaphor for that capital base.
The vehicle is specific: participating whole life, typically from a mutual carrier, designed for cash value rather than maximum death benefit. To see why the structure matters so much, it helps to know how whole life insurance cash value works. That one mechanic explains both why the strategy works over time and why it never breaks even on day one. Infinite banking is not a product. It is a strategy that uses one.
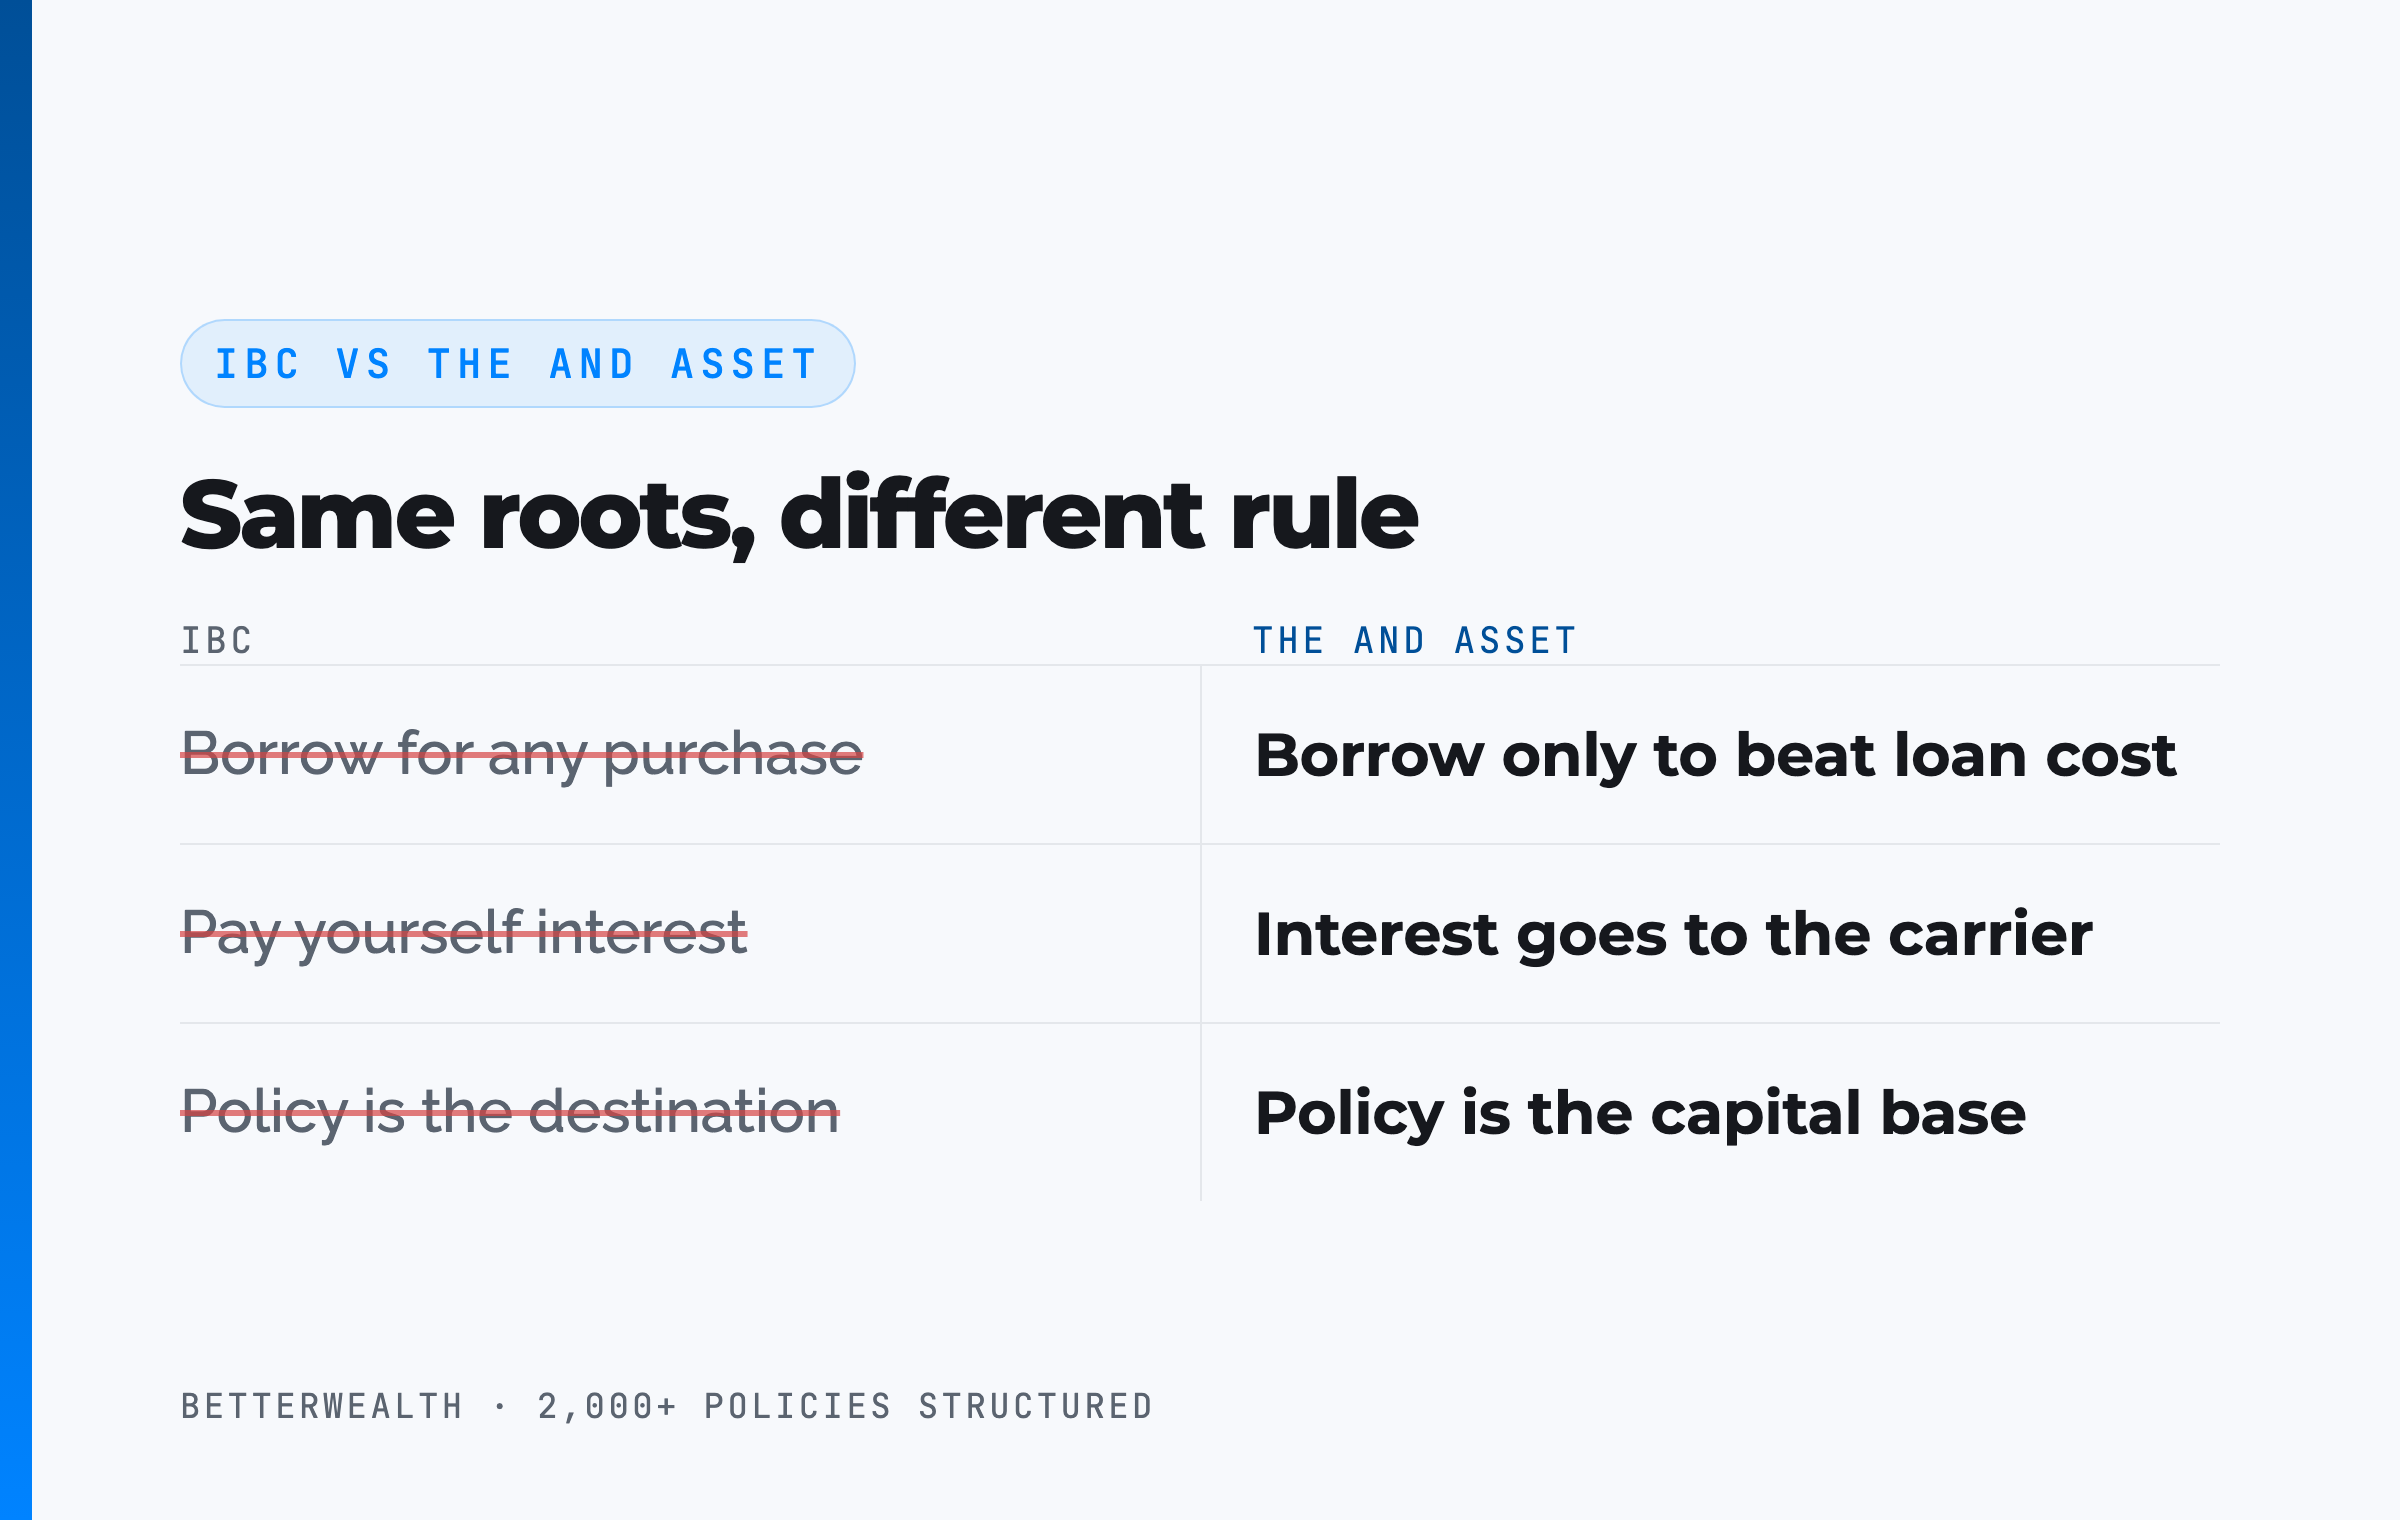
Nash is the pioneer, and we credit him in every piece we write on this. His insight about lost opportunity cost and the structural cost of paying interest to outside lenders is the foundation. What we practice and teach, The And Asset, shares roots with IBC but operates on different principles.
Where IBC ends and The And Asset begins
IBC says you can use a whole life policy as a personal banking system for any purchase, including consumption. The And Asset says you only deploy capital from the policy when the borrowed dollars will produce a return greater than the carrier's loan cost, such as a down payment on a rental that cash flows or inventory bought at a supplier discount. Anything less is an expensive way to spend money.
The policy is the capital base. The value is created in what you deploy that capital into.
The math has to work. Every time.
03 / The productWhy does infinite banking require a specially designed whole life policy?
The product behind infinite banking is a participating whole life policy, typically from a mutually owned carrier, deliberately structured to maximize early cash value rather than death benefit. This is the single most overlooked piece of the strategy, and most people have never seen a policy built this way. A policy your uncle's agent sold you for maximum coverage will not function as a capital base.
The design lever is the split between base premium and the paid-up additions rider. You minimize the base and load the PUA rider up to the Modified Endowment Contract (MEC) limit under Section 7702A, which front-loads cash value. A common structure runs a base-to-PUA ratio in the neighborhood of 40/60 or even 10/90, depending on the design goal. Get this wrong and the policy behaves like ordinary whole life: slow, expensive, and disappointing.
Two points need precision. First, the growth. Cash value does not compound at the headline dividend rate. It compounds at the dividend net of mortality and expense charges, which is the figure that actually accrues inside the policy. Second, "guaranteed growth for life" oversimplifies. A whole life policy carries a guaranteed cash value schedule plus non-guaranteed dividends declared annually by a mutual carrier's board. The guarantee and the dividend are two different things.
Your policy does not grow at the dividend rate. It grows at the dividend net of mortality and expense charges. Any agent quoting the gross rate as your return is careless or selling.
04 / How it worksHow does the infinite banking concept work, step by step?
The concept works through five steps, and the order is what makes it function. A mortgage and a home equity line are a fair analogy: you build equity, then access that equity through a loan while the underlying asset keeps its value. Here is the sequence we use when we structure one.
- Run income through the capital base first. Before you save, spend, or invest, route surplus cash flow into a policy you own and control. This is the behavioral core of the strategy. You become the first stop for your own capital.
- Structure for cash value. Minimize base premium, maximize the paid-up additions rider. The PUA rider is the engine. Without it, you own an expensive death benefit, not a capital base.
- Capitalize the policy. Fund consistently and let the early years build. First-year cash value lands below your contribution, and that is normal. Break-even typically lands around year five for a healthy individual; any illustration showing year one or two is fiction.
- Collateralize, do not withdraw. When you want capital, take a policy loan from the carrier's general account, collateralized by your cash value. The cash value stays in the policy and keeps compounding, though how the loaned portion is credited depends on the carrier's loan recognition method.
- Deploy and repay. Put the borrowed capital into an activity that beats the carrier's loan cost, then repay on your own schedule from the cash flow that activity throws off.
A well-designed policy reaches the capitalization point, where each premium dollar adds more than a dollar of cash value, often around year three in a PUA-heavy design. Break-even, where total cash value catches total contributions, typically lands at year five for a healthy individual. Not year one. Not year two.
The "you are not borrowing from yourself" correction
The most useful clarification in the video above is also the most misunderstood point in all of infinite banking. You are not borrowing from yourself. You take a loan from the insurance company's general account, and you collateralize it with your cash value. Your cash value never leaves the policy; the loan is the carrier's money. The interest you pay goes to the carrier, not back into your own pocket. The benefit is not that you "pay yourself interest." The benefit is that your cash value keeps compounding while you have capital deployed elsewhere. That is the entire mechanical advantage, and it survives precisely because the money stays put.
The infinite banking concept fits a specific person doing specific things.
It fits you if
- You already deploy capital and think in IRR
- You have surplus cash flow to fund consistently for 10+ years
- You can name a use for capital that beats the loan cost
- You want control and tax treatment over day-one liquidity
It does not fit you if
- You are early in building wealth and need every dollar liquid
- You want a savings account, not a life insurance strategy
- You are looking for a fix for high-interest debt
- You cannot identify a productive use for borrowed dollars
If you are in the first column, a 30-minute conversation will tell you whether the math works for your situation. If you are in the second, we will tell you that too.
Book a Discovery Call05 / The mathDoes the return clear the carrier's loan cost?
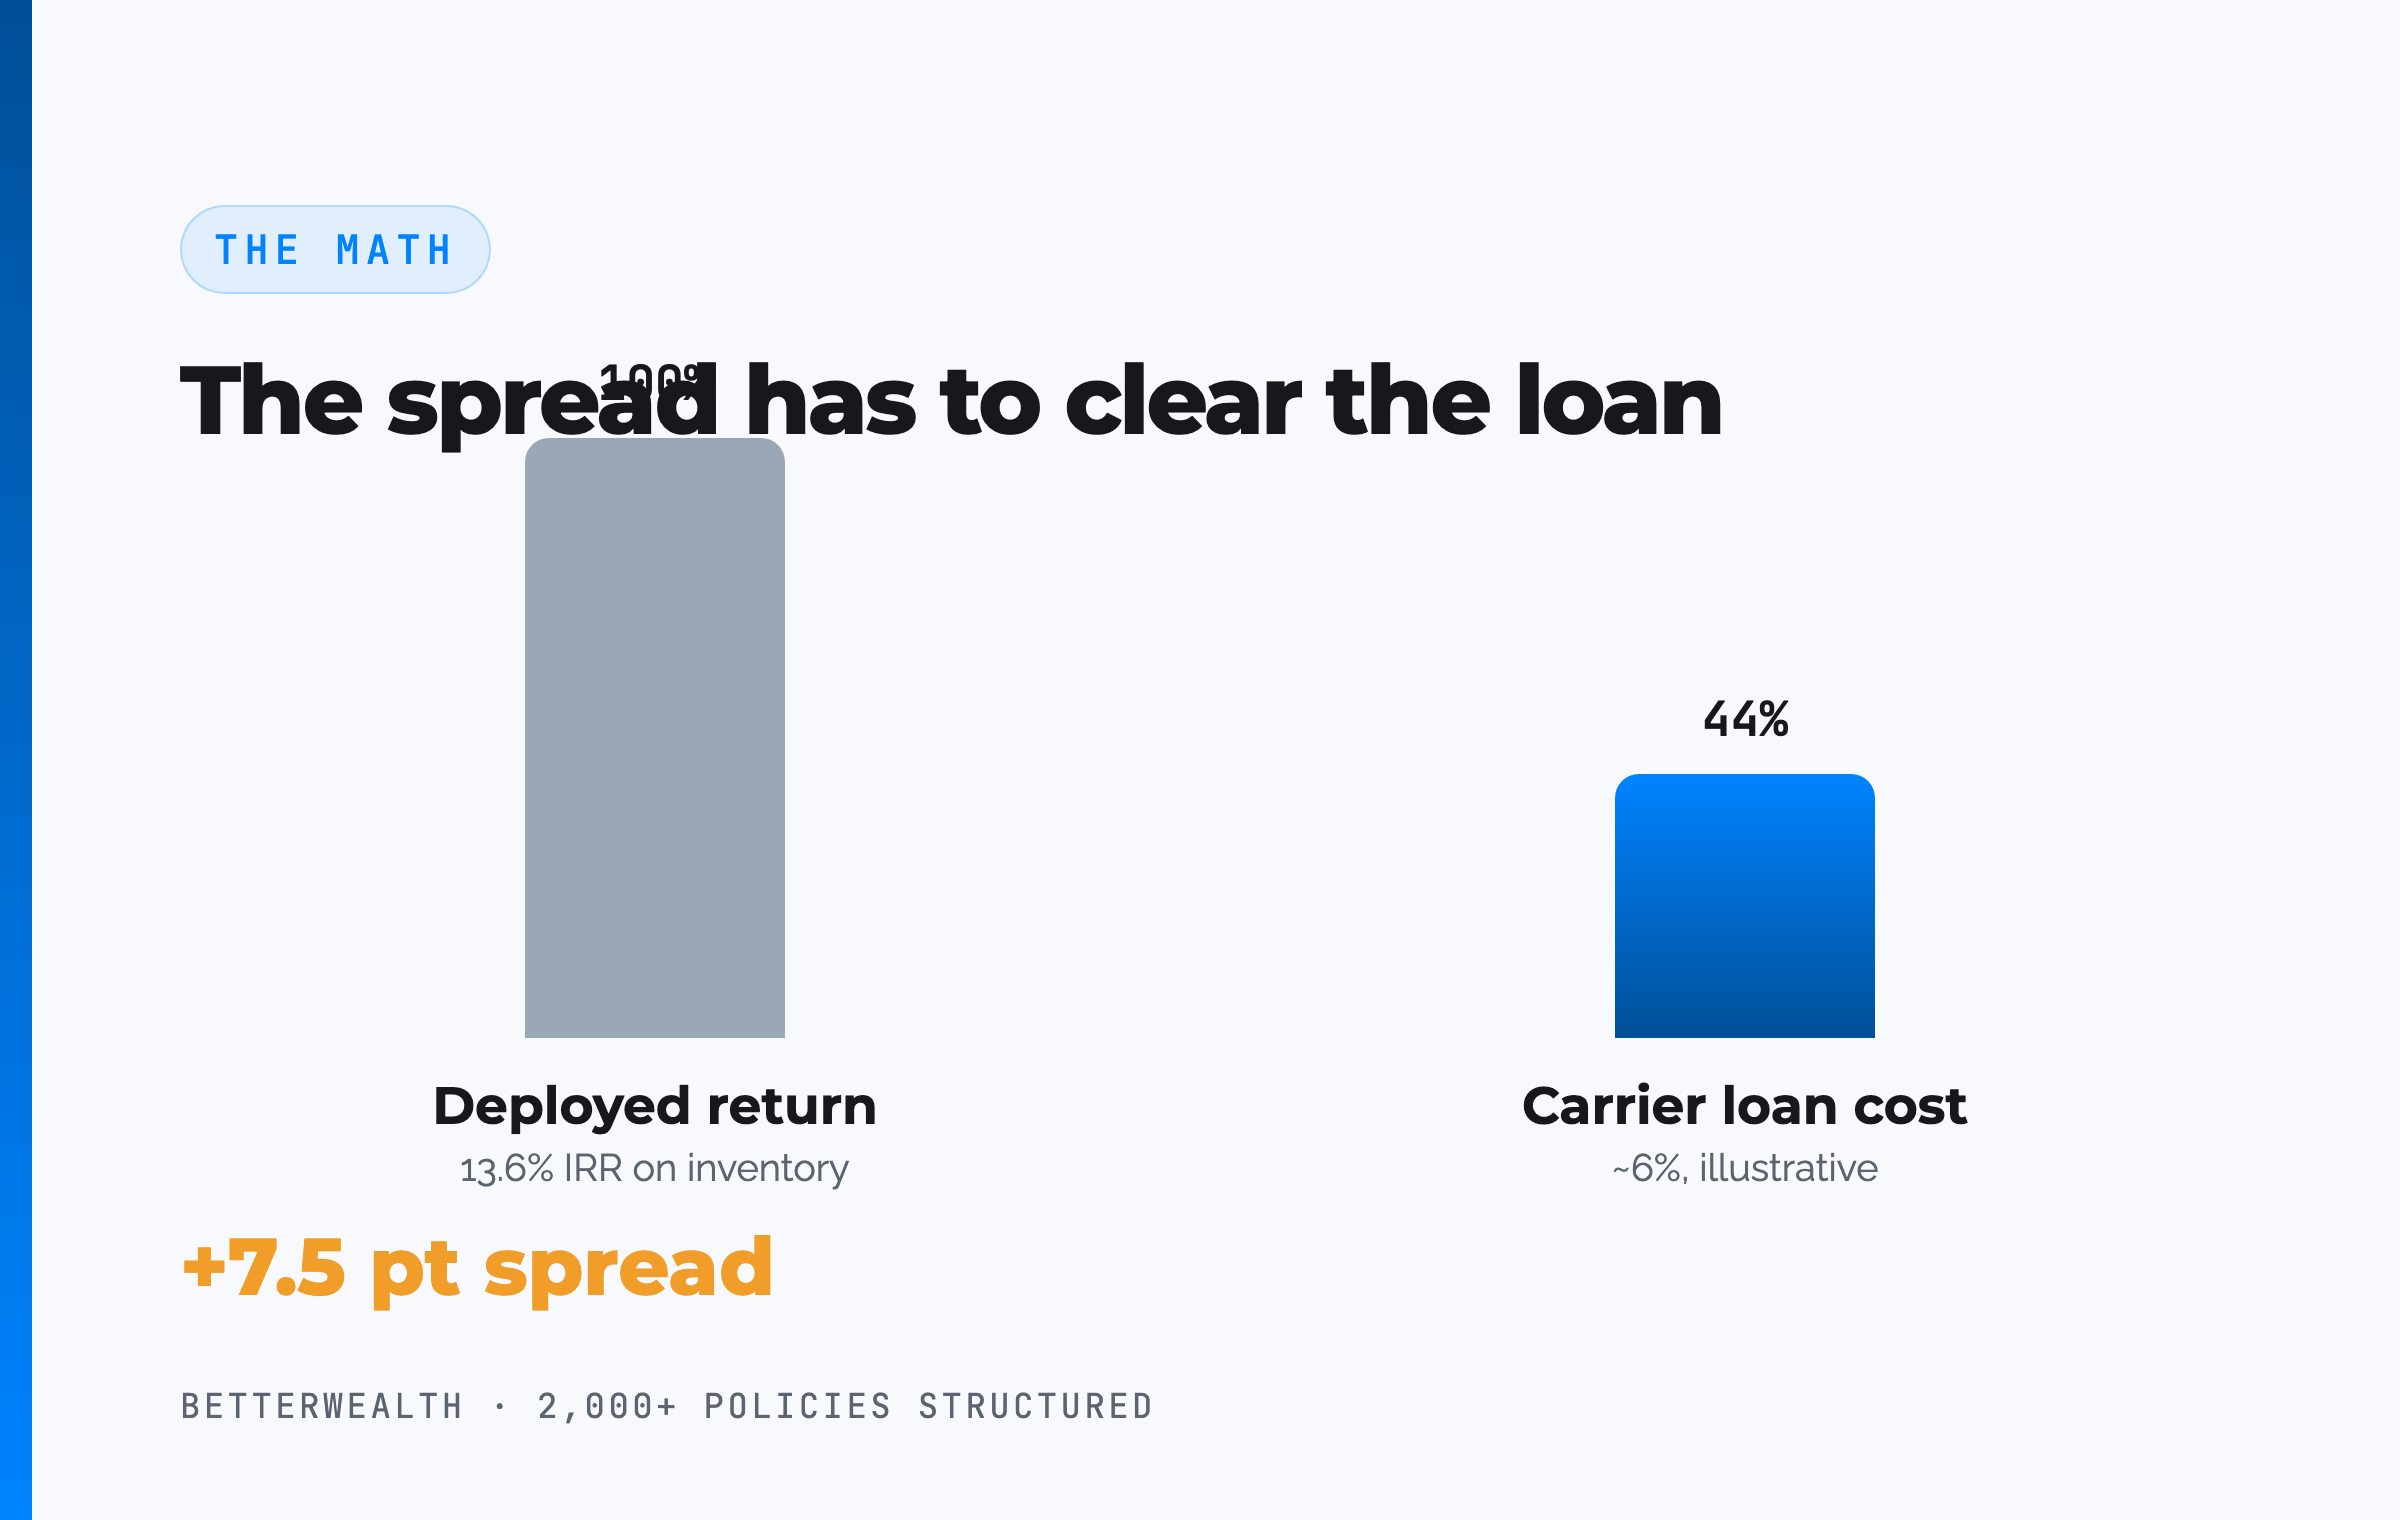
The return on whatever you deploy must exceed the carrier's loan cost, or you should not borrow. This is the test that separates a working strategy from an expensive habit. Policy loan rates vary by carrier and rate environment. At the time of writing, many carriers fall in the 5 to 6% range, but treat that number as a variable to verify with the carrier, not a constant.
Here is the structure of the decision. You borrow at the loan rate. Your policy keeps compounding, including on the borrowed portion. At a non-direct-recognition carrier the dividend on that portion is unchanged; at a direct-recognition carrier such as Guardian or Penn Mutual it is adjusted up or down while the loan is out. Your deployed capital earns its own return. If that return is higher than the loan cost, you are ahead on the spread, and one dollar has done two jobs. If the return is lower, you have paid the carrier's rate to earn less than it.
Our animation shows you can spend the borrowed money on "whatever you want," and notes, accurately, that this freedom can be as much a negative as a positive. The And Asset removes the ambiguity. The freedom is real. The discipline is what makes it pay.
If the deal does not clear the loan rate, do not borrow.
06 / The nine benefitsWhich of the "family bank" benefits hold up, and which need an asterisk?
Most of the commonly listed benefits hold up under scrutiny, and three of them need an asterisk. The usual list names nine: dividends, guaranteed growth, privacy, control, tax-free growth, leverage, protection, zero volatility, and an opportunity fund. As a list of why entrepreneurs use this, it is directionally right. As a set of literal promises, a few need precision.
Dividends, privacy, control, leverage, and the opportunity fund hold up, with privacy read narrowly. A mutually owned carrier pays dividends to policyholders, the contract is not a public record and is not held in a brokerage account, you control the asset, you can borrow against it, and accessible capital lets you close on an opportunity in days without waiting on a lender's approval. The three that need tightening are the ones that get people in trouble.
- "Tax-free growth" is more precisely tax-deferred growth, with policy loans generally not treated as taxable income when the policy meets the IRC Section 7702 definition of life insurance and stays out of MEC status under Section 7702A. The treatment depends on keeping the contract within federal limits and not lapsing it with a loan outstanding. Tax-advantaged with conditions, not unconditionally tax-free.
- "Guaranteed growth" blends two things. There is a guaranteed cash value schedule, and there are non-guaranteed dividends. Both matter. They are not the same promise.
- "Zero volatility, no losses ever" is true in the narrow sense that cash value is not invested in the market and does not drop when stocks drop. It is not a claim that the policy is costless. The early-year gap between cash value and premiums paid, and the cost of insurance, are real.
One benefit worth adding that the list leaves off: the death benefit itself, which protects your family from day one.
07 / Where people get this wrongWhere do marketers oversell infinite banking?
The most common failure is not a bad policy. It is a good concept stripped of its discipline and sold as free money. Marketers have ruined the way this strategy should be explained. The phrase "pay yourself interest" is the clearest tell. It is factually wrong. The interest goes to the carrier. Your return comes from what you deploy into, not from a circular payment to yourself.
The second failure is treating the strategy as universal. The strategy does not work without income. It also does not work without a productive use for borrowed capital. If you cannot identify an activity that beats the loan cost, the disciplined answer is to not borrow, and possibly to not buy the policy at all yet.
The third failure is "tax-free returns" with no mention of the rules. The favorable tax treatment exists under specific limits, including the Modified Endowment Contract line, and it is not unconditional. A pitch that skips the conditions is skipping the part that protects you.
The skeptic is right to push back on the hype. Whether the underlying product belongs in a plan at all is its own question, which we take on in is whole life insurance worth it. The short version: it is worth it only when it is designed for cash value and used by someone who deploys borrowed capital into returns that beat the loan cost.
This is not for everyone. If you are looking for a savings account with a better rate, this is the wrong tool, and a good practitioner will tell you so before you sign anything.
The frameworks behind 2,000+ policies, in one place.
The And Asset Vault holds the calculators, design frameworks, interviews, and the handbook we use to structure policies and pressure-test the math before anyone funds one. Free, email-gated, no spam.
Open the Vault08 / Head to headFamily bank versus a HELOC and a savings account
Compared to a HELOC or a savings account, a specially designed whole life policy used The And Asset way trades day-one simplicity for control, compounding, and tax treatment. Against a HELOC it has three real advantages: you own it, it is designed to grow, and there is no required repayment. The table sets the concept against a HELOC and an ordinary savings account on the dimensions that matter.
| Dimension | Specially designed whole life | HELOC | Savings Account |
|---|---|---|---|
| Growth | Keeps compounding, net of internal costs, while borrowed against; dividend on the loaned portion depends on the carrier's loan recognition | The credit line itself earns nothing; any growth is in the underlying property | Low interest, taxed annually |
| Access | Policy loan collateralized by cash value, no approval, no required repayment schedule | Fast once approved, but can be frozen or called | Immediate, fully liquid |
| Control | You own it; the loan is not called while the policy stays in force; you set repayment, but unpaid interest adds to the balance | Lender controls terms and can revoke access | Full control, but no leverage feature |
| Tax treatment | Tax-deferred growth; loans generally not taxable income while the policy qualifies under 7702, stays non-MEC and stays in force | Interest deductible only in narrow cases; verify with a tax advisor | Interest taxed as ordinary income |
Growth. The policy keeps compounding while you borrow (how the loaned portion is credited depends on whether the carrier uses direct or non-direct recognition), which a HELOC cannot do because a credit line is not an asset, and which a savings account cannot match because the interest is low and taxed. Uninterrupted compounding is the structural feature that lets one dollar do two jobs.
Access and control. A HELOC is faster on paper, and a HELOC can be frozen or reduced by the lender, often when credit tightens. A policy loan is not called while the policy stays in force, and there is no required monthly payment. The constraint: interest accrues, and if the loan plus interest grows past the cash value, the policy lapses and the gain can become taxable. The freedom is real, and The And Asset insists on managing it.
Tax treatment. Policy loans are generally not taxable income while the policy meets the Section 7702 definition, stays out of MEC status and stays in force, while savings interest is taxed every year. The And Asset trades the absolute simplicity of a savings account for control and tax treatment you keep.
A composite: the business owner who waited until the math worked
Consider a 39-year-old business owner, preferred non-tobacco, funding a specially designed whole life policy at $42,000 per year, with most of the premium going to the paid-up additions rider. This is a representative composite, not a single named client, and the figures assume current non-guaranteed dividend scales, so treat them as illustrative rather than a projection.
Through the first four years, cash value trails cumulative contributions, exactly as a real policy should. The heavy paid-up additions rider is why year one starts this high; break-even still waits for year five because the base premium and the cost of insurance hold each early year's credit below a dollar per dollar paid until the policy capitalizes. By year three, each premium dollar adds more than a dollar of cash value. At year five, total cash value crosses total contributions. No earlier. Any illustration showing year-two break-even is marketing fiction.
In year six, with roughly $268,000 of accessible cash value, the owner borrows $94,500 against the policy to buy inventory at a supplier discount ahead of a seasonal run. The inventory turns at a margin that returns an estimated 13.6% IRR. The loan cost is illustrative at around 6%, so the spread works in the owner's favor by roughly seven and a half points. The policy keeps compounding the entire time, with the dividend on the loaned portion set by the carrier's loan recognition method. Repayment runs on a 31-month schedule funded by the sales the inventory generates.
One dollar. Two jobs. That is the And.
09 / The bigger pictureHow the concept fits into a broader life insurance strategy
The infinite banking concept is a capital-structure tool, not a financial plan, and it works best as one component inside a strategy that already has cash flow, deployable opportunities, and a long horizon. The policy is the base. Real estate, business reinvestment, equipment, and acquisitions are where the return is created. The policy does not replace those activities. It finances them while continuing to compound.
This is why the early question is never "which carrier has the highest dividend." It is whether you have surplus cash flow to fund consistently, a use for borrowed capital that beats the loan cost, and the patience to let the early years capitalize. Get those right and the concept becomes a quiet engine underneath the rest of your capital. Get them wrong and no policy design will save it.
That is why entrepreneurs and high-income earners are the people who stay with it. They already deploy capital, and they feel the cost of slow access more sharply than savers do. For them the appeal is not a high dividend. It is control, tax treatment, and uninterrupted compounding together. For the high-income earner who has maxed every tax-advantaged account, it adds a kind of access that another brokerage position does not.
The honest 30 minutes about whether this fits you.
We have structured more than 2,000 policies across all 50 states. We have seen this strategy work exactly as designed, and we have seen it fail when there was no productive use for the capital. On a discovery call, a practitioner looks at your specific situation and tells you the honest answer either way. If you would rather learn first, The And Asset and BetterWealth YouTube channels go deep on the math.
Book a Discovery CallFAQInfinite banking concept questions
What is the infinite banking concept?
The infinite banking concept is a strategy that uses a specially designed whole life insurance policy as a personal capital base you can borrow against. Coined by Nelson Nash, the idea is to recapture the banking function in your own financial life instead of losing it to outside lenders or to the opportunity cost of idle capital.
Is infinite banking legit or a scam?
Infinite banking is a legitimate use of a real financial product, but it has been oversold. The mechanics are real: a whole life policy builds cash value you can borrow against. The scam-like claims come from marketers who promise tax-free wealth, paying yourself interest, or a savings account that beats the market. The honest version is narrower and depends entirely on the math.
How much money do you need to start infinite banking?
There is no single minimum, but the strategy fits people who can fund a policy consistently for a decade or more and who already deploy capital. If you cannot fund the policy steadily or cannot identify a use for borrowed capital that beats the loan cost, the strategy does not work as designed.
What is The And Asset?
The And Asset is BetterWealth's framework for using a properly structured whole life policy as a capital base. You only borrow against it for an activity that produces a return greater than the carrier's loan cost, so your dollars do two jobs at once: the policy keeps compounding while the deployed capital earns its own return. Nelson Nash's infinite banking concept is its starting point.
How is The And Asset different from infinite banking?
Infinite banking, as Nelson Nash taught it, frames a whole life policy as a personal banking system for any purchase. The And Asset frames the policy as the capital base, not the destination, and only deploys capital when the borrowed dollars out-earn the carrier's loan cost. It shares roots with IBC but operates on different principles.
Are you borrowing from yourself with infinite banking?
No. You are not borrowing from yourself. You take a loan from the insurance company's general account and collateralize it with your cash value. Your cash value stays in the policy and keeps compounding, though the dividend on the loaned portion depends on whether the carrier uses direct or non-direct recognition. The loan interest is paid to the carrier, not back to you.
What kind of life insurance is used for infinite banking?
A specially designed participating whole life policy, typically from a mutually owned carrier, structured to maximize early cash value through a heavy paid-up additions rider and a minimized base premium. A policy sold for maximum death benefit will not function well for this strategy.
Is the growth in a whole life policy really tax-free?
Cash value grows tax-deferred, and policy loans are generally not treated as taxable income when the policy meets the IRC Section 7702 definition of life insurance and stays out of MEC status under Section 7702A. The tax treatment depends on keeping the contract within those limits and not letting it lapse with a loan outstanding. It is tax-advantaged with conditions, not unconditionally tax-free.
How fast does cash value build in a whole life policy?
Even a well-designed policy does not break even in year one or two. Cash value typically trails cumulative contributions through the first few years, reaches the point where each premium dollar adds more than a dollar of value around year three, and crosses total contributions around year five for a healthy individual.
Why does a mutually owned insurance company matter?
A mutual company is owned by its policyholders rather than outside shareholders, so dividends are paid to policy owners. Whole life dividends are declared annually by the board and are not guaranteed, but a strong mutual carrier with a long dividend history is the foundation most infinite banking designs are built on.
Is infinite banking the same as a savings account?
No. A savings account stores money safely at a low return. The And Asset is a life insurance strategy where the same dollar compounds inside the policy while borrowed capital is deployed into something that beats the loan cost. If you only want to store money, this is the wrong tool.
Who is the infinite banking concept actually for?
It fits entrepreneurs, business owners, real estate investors, and high-income earners who already deploy capital and can identify uses for borrowed dollars that outperform the loan cost. It is not a starting point for early-stage savers or a fix for high-interest debt.
What does it mean to collateralize a policy loan?
Collateralizing means the carrier lends you money using your cash value as security, the same way a home equity line uses your house. The loan comes from the insurer's funds, your cash value remains intact and continues to grow (with the loaned portion credited according to the carrier's loan recognition method), and there is no required monthly repayment schedule. Interest does accrue, and if the loan plus interest grows past the cash value, the policy lapses and the gain can become taxable.
Can I lose money in a whole life policy from market drops?
Whole life cash value is not invested in the market, so it does not fall when stocks fall. Guaranteed cash value plus declared dividends grow the policy net of mortality and expense charges. The real costs to watch are the early-year gap between cash value and premiums paid, the cost of insurance, and the discipline required to use loans productively.
- Nelson Nash, Becoming Your Own Banker, the origin of the infinite banking concept.
- IRC Section 7702 (Cornell Law), the tax code definition of life insurance that its tax treatment rests on.
- BetterWealth resources: The And Asset book, The And Asset YouTube channel, and the BetterWealth YouTube channel.
I founded BetterWealth to treat life insurance as the wealth and capital tool it actually is, not the product most people get sold. Our team has structured more than 2,000 policies across all 50 states. I wrote The And Asset and host the BetterWealth and The And Asset YouTube channels. If you want an honest read on whether the infinite banking concept fits your plan, book a discovery call. We will tell you if it does not.