The infinite banking concept is a strategy, named by Nelson Nash, of using a dividend-paying whole life policy designed for high cash value as your own source of financing: you borrow from the insurance company against the cash value instead of from a bank, and the cash value keeps growing while the loan is out. It works only if the policy is built for cash value and the borrowed money earns more than the loan costs.
What is the infinite banking concept? In one line: own a whole life policy built to hold as much cash value as the tax rules allow, and borrow against it when you need capital, so the same dollars stay in the policy compounding while the loan proceeds go to work somewhere else. Nelson Nash laid it out in Becoming Your Own Banker. The mechanics are real. Most of what goes wrong comes from how it is sold.
Three things the simple explanations leave out decide whether it works for you: how the policy is designed, what the loan really costs at your carrier, and whether you have a use for the money that beats that cost. This guide covers all three with figures from our 2026 carrier guide and a real case from one of our calls.
- Infinite banking uses a participating whole life policy designed for cash value, with most of the premium going to a paid-up additions (PUA) rider, as a pool of capital you borrow against.
- You are not borrowing from yourself. The loan comes from the carrier, your cash value is the collateral, and the interest goes to the carrier.
- Year-one cash value runs about 70% to 93% of the premium paid, depending on carrier and design, and total cash value typically catches total premiums around year 5 or later.
- Long-term projected returns run about 3.5% to 5.3% on high cash value designs. That is a return for safe money, not a market return.
- Direct recognition carriers (Penn Mutual, Guardian) credit the borrowed portion differently; non-direct carriers (MassMutual, New York Life, Lafayette Life, OneAmerica) do not.
- The And Asset rule: borrow only when the deployed return beats the carrier's loan cost. Otherwise, do not borrow.
Our short animation draws the whole idea on one page, from income flowing into the policy to the loan going out. Watch it for the picture, then read on for the numbers a short video has no room for.
01 / The problemWhat problem is infinite banking trying to solve?
Every time you finance something, you either pay interest to a lender or pay cash and give up what that cash would have earned. Nash's point was that most people do both at once: they finance cars, homes and businesses through banks while their reserves sit in accounts earning little. He called the fix taking back the banking function in your own life.
For a business owner or investor the problem is sharper. When a deal shows up, getting money means selling something and paying tax, or asking a lender who can say no or freeze a credit line when credit tightens. Infinite banking answers that with a pool of capital you control, that keeps growing, and that you can borrow against without an approval.
The question is not where to park money. It is who you borrow from when an opportunity shows up, and what that borrowing costs.
02 / The frameworkWhat does the infinite banking concept actually mean?
It means treating a whole life policy as a capital base rather than only as a death benefit. You fund the policy, the cash value builds, and when you need money you take a policy loan against it instead of going to a bank. The policy is the vehicle; infinite banking is the way you use it. It is a strategy, not a product, and no carrier sells a policy called "infinite banking."
Nash is the pioneer, and we credit him every time. What we practice and teach, The And Asset, is BetterWealth's own framework. It shares Nash's roots but operates on a different rule.
Where IBC ends and The And Asset begins
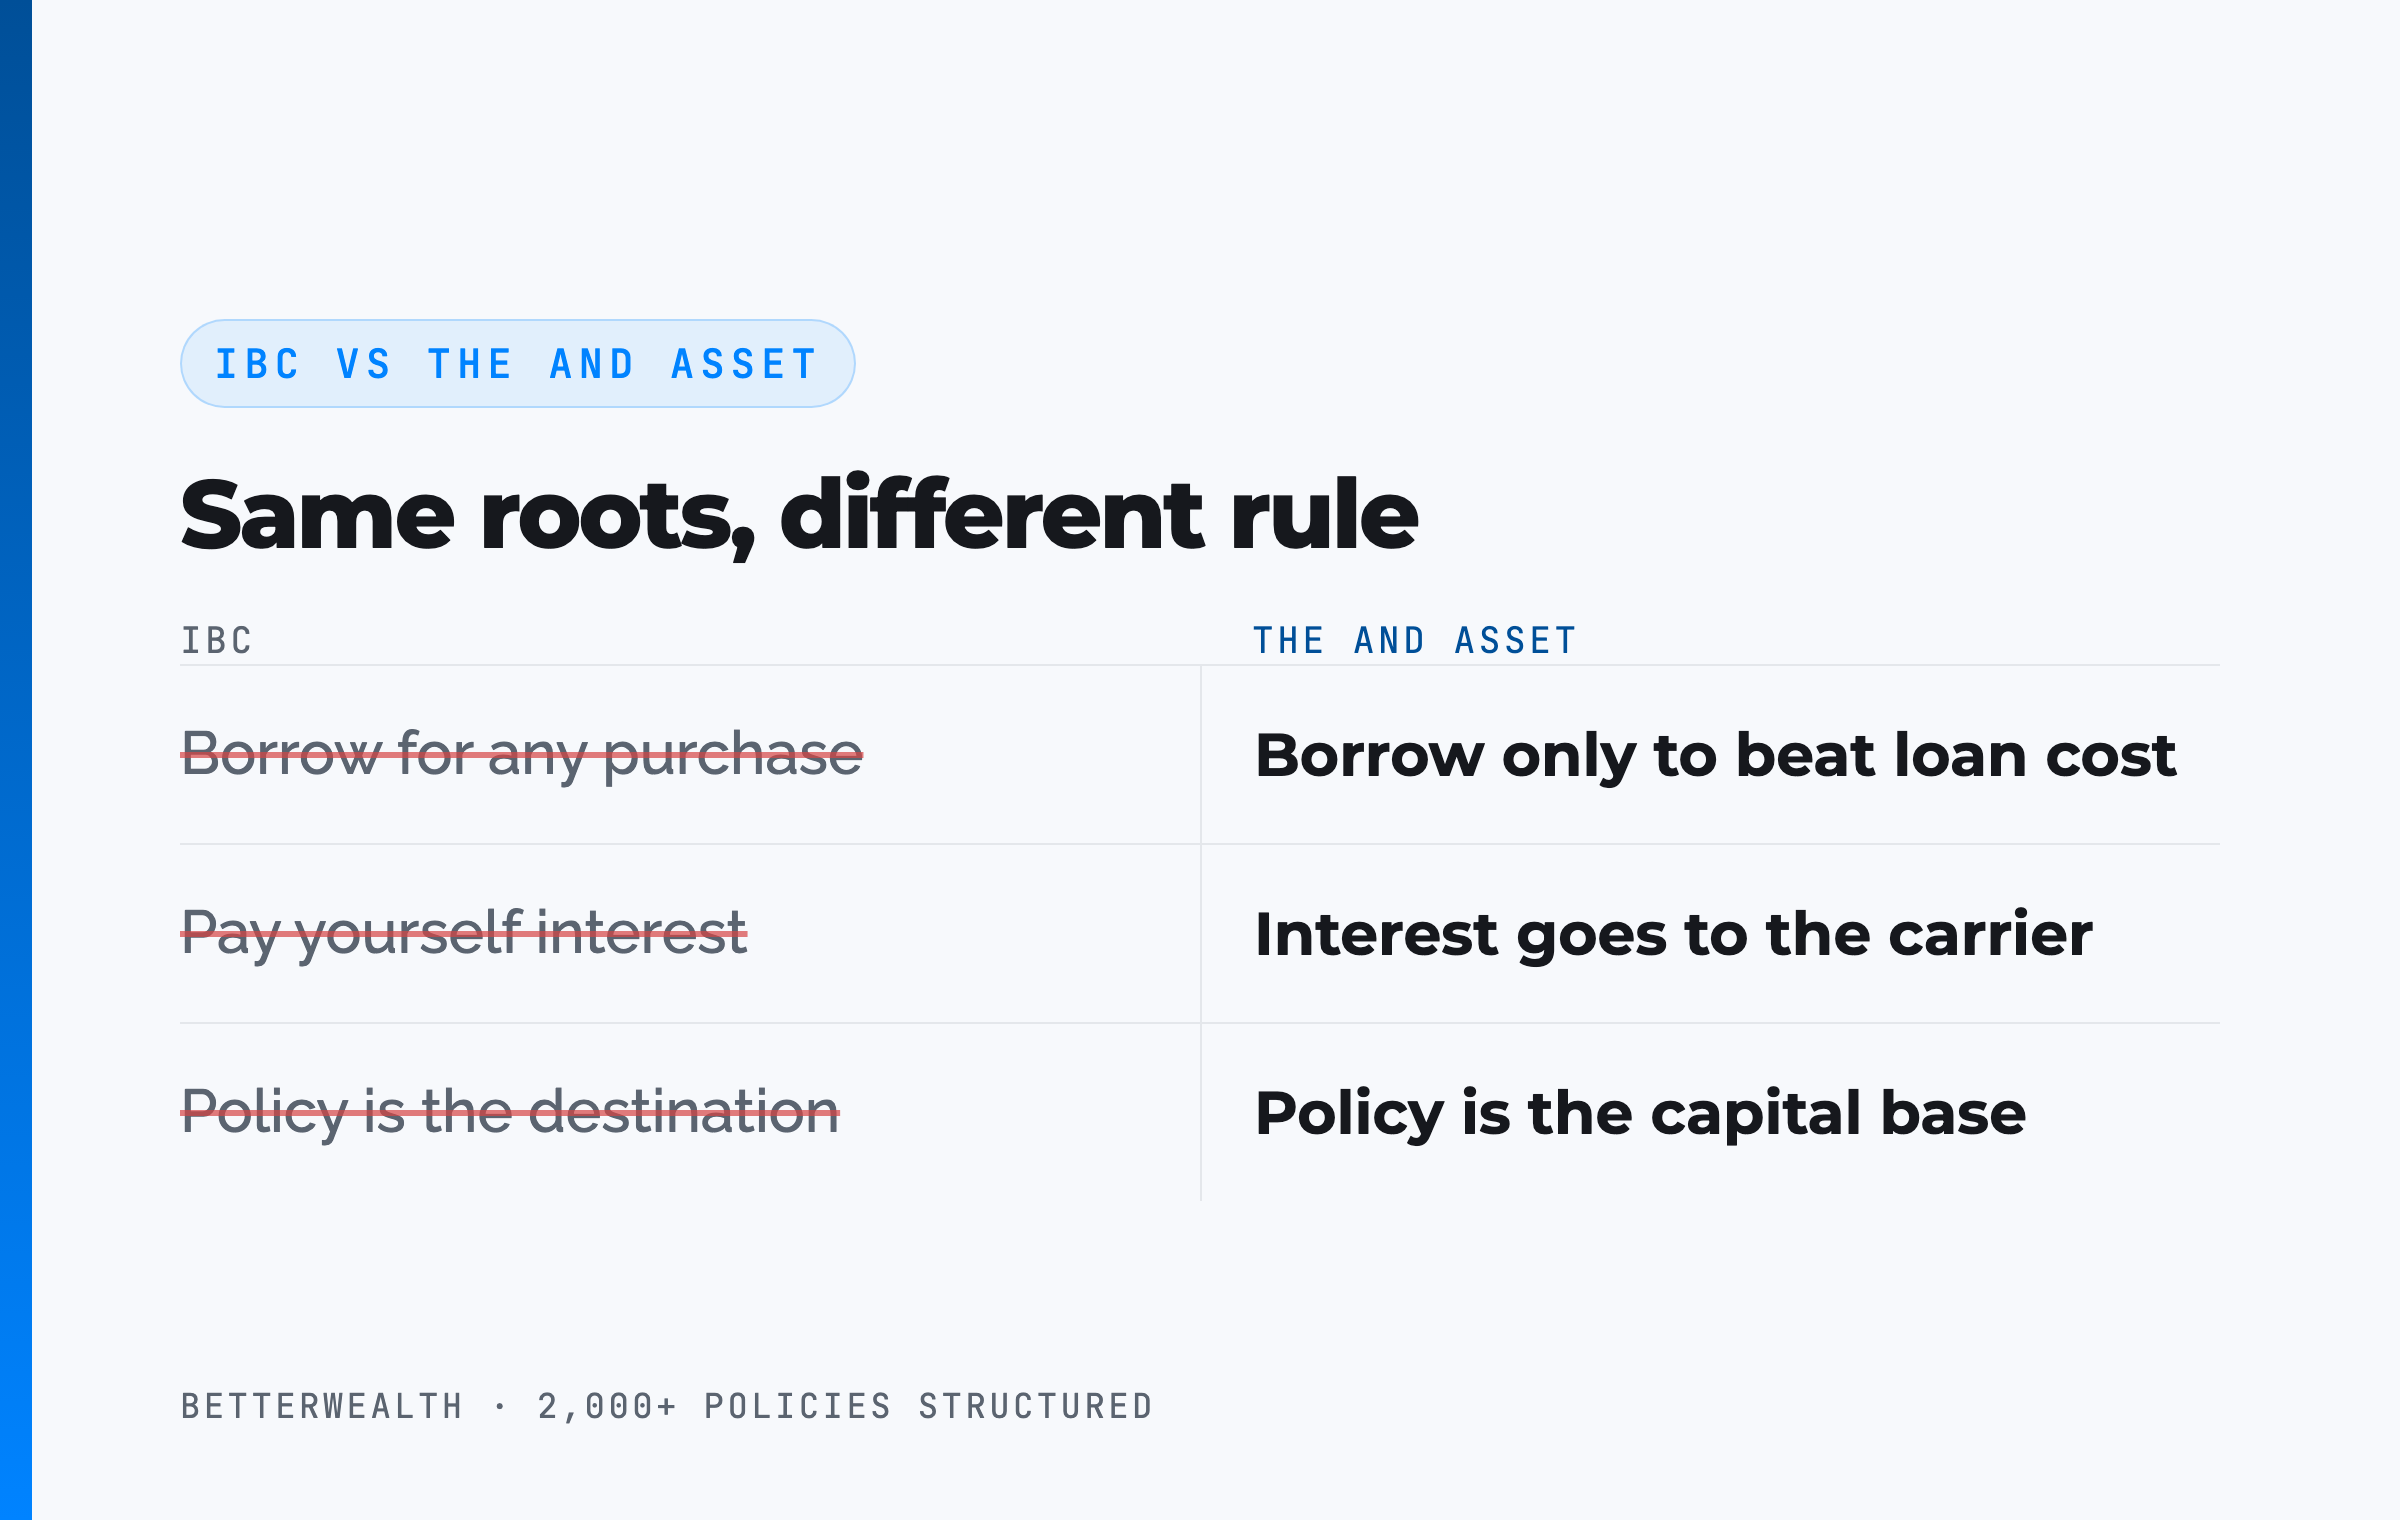
IBC, as it is commonly marketed, says use the policy as a personal bank for any purchase. The And Asset says the policy is the capital base, and you borrow only when the deployed dollars out-earn the carrier's loan cost, because a loan that does not clear that cost leaves you paying the carrier more than the capital earns. When it does clear, your dollars do two jobs: the cash value keeps compounding, net of mortality and expense charges, and the borrowed capital earns its own return. That is the AND.
The math has to work. Every time.
03 / The policyWhat kind of policy does infinite banking use?
A participating (dividend-paying) whole life policy, usually from a mutual carrier, designed for cash value rather than for the largest death benefit. Term insurance has no cash value, so it cannot be used. A whole life policy sold the ordinary way, for maximum coverage per premium dollar, builds cash value too slowly to borrow against for years.
The design lever is the split between base premium and the paid-up additions rider, written base/PUA. A smaller base and a larger PUA share puts more of each premium into cash value early, up to the modified endowment contract (MEC) limit set by the 7-pay test in IRC Section 7702A. Our 2026 carrier guide calls Ameritas ideal for 40/60 designs, for example. We cover the design choices in how to structure an infinite banking policy and the rider itself in paid-up additions explained.
Two pieces of language need precision. Cash value does not grow at the carrier's headline dividend rate; it grows at the dividend net of mortality and expense charges. And "guaranteed growth" blends two things: a guaranteed cash value schedule in the contract, and dividends the carrier's board declares each year, which are not guaranteed.
How much cash value is there in year one?
Less than you paid in. Our 2026 carrier guide puts year-one cash value at about 70% to 93% of the first year's premium across nine carriers, depending on carrier and on whether the policy is level-funded or front-loaded. Total cash value then typically catches total premiums paid around year 5 or later for a healthy person. An illustration showing break-even in year one or two deserves a hard second look.
The dividend rate is not your return. MassMutual declared the highest 2026 dividend interest rate in our guide, 6.6%, and the guide notes it generally does not have the most competitive growth.
04 / How it worksHow does infinite banking work, step by step?
It works in five steps, and the order matters. Think of a house and a home equity line: you build equity, then borrow against it while the house stays yours. Here is the sequence.
- Design for cash value. Keep the base premium low and put most of the premium into the paid-up additions rider, staying under the MEC limit.
- Fund it consistently. Plan to fund for 10 years or more. The early years carry the cost, so a policy dropped early locks in the worst part of the curve.
- Let the cash value build. Expect cash value below premiums paid until around year 5 or later. A first loan is usually available within about 10 to 45 days of funding, depending on carrier, but the amount is limited to a share of the cash value.
- Borrow against it, do not withdraw. Take a policy loan from the carrier, using your cash value as collateral. The cash value stays in the policy and keeps compounding, credited according to the carrier's loan recognition method.
- Deploy and repay. Put the money into something that earns more than the loan costs, and repay on your own schedule from what it earns.
Are you really borrowing from yourself?
No. This is the most repeated mistake in infinite banking marketing. The loan is the insurance company's money, your cash value is the collateral, and the loan interest goes to the carrier, not back to you. Repaying the loan restores what you can borrow next time; it does not pay you interest. The real advantage is narrower and still valuable: your cash value keeps compounding while borrowed money works somewhere else.
Infinite banking fits a specific person doing specific things.
It fits you if
- You already deploy capital in a business or real estate
- You can fund a policy for 10+ years
- You can name a use for capital that beats the loan cost
- You want control of capital more than maximum yield
It does not fit you if
- You may need the money within a few years
- You want a stock market alternative
- You want it to fix high-interest debt quickly
- You have no productive use for borrowed money
If you are in the first column, a discovery call will show whether the math works for your situation and how the policy should be designed. If you are in the second, we will tell you that too.
Book a Discovery Call05 / The loanDoes it matter which carrier you borrow from?
Yes, because carriers credit borrowed cash value in two different ways. At a non-direct recognition carrier, the dividend is the same whether or not part of the cash value is borrowed against. At a direct recognition carrier, the dividend on the borrowed portion is adjusted while the loan is out, down or sometimes up depending on the carrier's design.
| Carrier | Loan recognition | Loan terms we can source | 2026 dividend interest rate | Projected long-term IRR |
|---|---|---|---|---|
| Penn Mutual | Direct | Guaranteed 0.65% spread between loan rate and dividend rate in years 1 to 10, 0% from year 11 | 6.1% | 4.2% to 5.3% |
| Guardian | Direct | Fixed 5% loan rate for the first 10 years; loans as soon as 30 days after funding | 6.25% | 3.5% to 4.5% |
| MassMutual | Non-direct | Check the current rate with the carrier | 6.6% | 3.8% to 4.9% |
| New York Life | Non-direct | Check the current rate with the carrier | 6.4% | 3.6% to 4.7% |
| Lafayette Life | Non-direct | Variable loan rate; loans 30 days after funding | 5.9% | 3.5% to 4.7% |
Source: BetterWealth 2026 IBC Carrier Comparison Guide and our carrier fact sheet. Dividend rates are declared each year and are not guaranteed; IRR ranges assume current dividend scales hold. Ameritas lets the owner choose direct or non-direct recognition.
Neither method is better on its own. On one of our calls, a BetterWealth coach described running the same client through MassMutual (non-direct) and Guardian (direct) with one or two loans repaid over 10 to 15 years: with the loans in, MassMutual's projected numbers "basically stayed exactly the same," while Guardian's came out "a relatively significant percentage lower." For a different borrowing pattern the answer can flip. In the coach's words, "that's the type of comparison we need to make before we make a choice."
06 / The mathWhen does borrowing against the policy make money?
Only when what you do with the money earns more than the loan costs. This is the test that separates a working strategy from an expensive habit. Loan rates differ by carrier and change with the rate environment, so get the current rate from your carrier and treat it as the hurdle.
A worked example, with an illustrative use: borrow $100,000 at Guardian's fixed 5% loan rate and lend it on a six-month note at a 15% annual rate. Over the six months the note earns $7,500 and the loan costs $2,500 in interest, so you keep a $5,000 spread, before tax and assuming the borrower pays, while the cash value keeps compounding under the carrier's crediting method. Put the same $100,000 into something that earns 4% and you are behind, and the right answer was not to borrow.
Two tax rules keep this honest. A loan from a policy that is not a modified endowment contract is generally not taxable income while the policy stays in force (IRC 72(e)). But if the policy lapses or is surrendered with a loan outstanding, the loan is generally treated as an amount received, and the amount by which the gross cash value (including the part used to pay off the loan) exceeds your basis (generally premiums paid, less tax-free amounts already received) is generally taxable as ordinary income. A policy funded past its 7-pay limit becomes a modified endowment contract: its loans are generally taxed gain-first, and the taxable part of a distribution before age 59½ can generally carry a 10% additional tax (IRC 72(v)). Check your own situation with a tax advisor.
If the deal does not clear the loan rate, do not borrow.
The investor who wanted "the best product for infinite banking"
A 64-year-old real estate investor who also lends to house flippers booked a call after finding BetterWealth on YouTube. The booking form asked for "the best product for infinite banking, funding it over 10 years, kind of borrow often." The investor had used a cash value policy this way before, borrowing from an old variable life policy "4 or 5 times" for real estate and debt: "And I always paid myself back." The investor had also been sold an indexed universal life policy as infinite banking, and about two years in, "the surrender value showing up is zero."
Our coach's order of priorities for someone who will borrow often: "I lean into the highest cash value first, probably," then the direct or non-direct recognition feature, then the loan rate. The coach's recommendation was to illustrate Guardian, Penn Mutual and Lafayette Life on "the same exact sort of funding and loaning schedule" and compare them side by side before choosing.
Six-month notes at 15% are the kind of use The And Asset test is built for: they clear a 5% loan rate by a wide margin, as long as the borrowers pay. What the investor called paying themselves back is really repaying the carrier, which is fine. The return comes from the notes, not from the repayment.
One dollar. Two jobs. That is the test.
07 / The claimsWhich infinite banking claims hold up, and which do not?
Most of the usual list holds up with conditions, and three claims do not hold as stated.
- "You pay yourself interest." Does not hold. The interest goes to the carrier.
- "Tax-free growth." Holds with conditions. Growth is tax-deferred, and loans are generally not taxable while the policy stays in force and is not a MEC. A lapse with a loan outstanding can create a tax bill.
- "Guaranteed growth." Partly. The guaranteed cash value schedule is guaranteed; dividends are not.
- "It works for any purchase." Does not hold. Borrowing for something that earns less than the loan cost loses money slowly.
- "No market losses." Holds in the narrow sense that whole life cash value is not invested in the market. It does not mean no cost: the early years trail premiums paid.
- Control, no required repayment schedule, privacy of the contract. Hold. The trade-off is that unpaid interest adds to the loan balance.
The skeptics who rank for this search are right about the oversold version, and we take on the strongest objections in is infinite banking a scam and infinite banking pros and cons. Whether the policy itself belongs in your plan is a separate question, answered in is whole life insurance worth it.
If you are looking for a savings account with a better rate, this is the wrong tool, and a good practitioner will tell you so before you sign anything.
Free infinite banking resources and education.
The Life Insurance Vault is where we keep free whole life and infinite banking resources and education, for anyone who wants to learn more before deciding whether a policy fits.
Open the Vault08 / ComparedHow does infinite banking compare with a HELOC or a savings account?
A policy used this way trades day-one liquidity and raw return for control, tax treatment and compounding that continues while you borrow.
| Dimension | Whole life used as a capital base | HELOC | Savings account |
|---|---|---|---|
| Growth | About 3.5% to 5.3% projected long-term, net of internal costs; keeps compounding while borrowed against | None; a credit line is not an asset | Low interest, taxed each year |
| Access | Policy loan up to the carrier's limit on cash value; no approval, no required repayment schedule | Fast once approved, but the lender can freeze or reduce it | Immediate |
| Early years | 70% to 93% of year-one premium in cash value; break-even around year 5 or later | Depends on home equity | Full balance from day one |
| Tax | Loans generally not taxable while in force and not a MEC (IRC 72(e)) | Interest deductible only in narrow cases; verify with a tax advisor | Interest taxed as ordinary income |
Against a HELOC, the policy cannot be frozen by a lender and it grows while you borrow. The HELOC wins on day-one cost: there is no early-years lag. We go deeper in infinite banking vs a HELOC.
Against a savings account, the account is fully liquid from day one and the policy is not. Over a long hold, the policy can come out ahead on safe money, after tax, but only if you keep it past the early years.
09 / Already own oneWhat if you already own a policy sold as infinite banking?
Find out what it is actually doing before you fund it further or drop it. The investor in our case was sold an indexed policy as infinite banking and found no surrender value two years in. Three questions tell you most of what you need: what was the policy designed to do (death benefit or cash value), how much of each premium goes to base, paid-up additions and term, and what surrendering it would cost you now, including tax on any gain and any outstanding loan.
FAQInfinite banking concept questions
What is the infinite banking concept?
It is a strategy, named by Nelson Nash, of using a dividend-paying whole life policy designed for high cash value as your own source of financing. You borrow from the insurance company against the cash value instead of from a bank, and the cash value keeps growing while the loan is out.
How does infinite banking work?
You fund a whole life policy designed with a low base premium and a large paid-up additions rider, let the cash value build, then take policy loans against it and repay them on your own schedule. It only makes money when the borrowed funds earn more than the loan costs.
Is infinite banking legit or a scam?
It is a legitimate use of a real contract, but it is often oversold. The mechanics work; the problems are claims that you pay yourself interest, that growth is unconditionally tax-free, or that it works for any purchase.
Are you borrowing from yourself with infinite banking?
No. The loan comes from the insurance company, your cash value is the collateral, and the interest goes to the carrier. Your cash value stays in the policy and keeps compounding, credited according to the carrier's direct or non-direct recognition method.
What kind of life insurance is used for infinite banking?
A participating whole life policy, usually from a mutual carrier, designed for cash value with a large paid-up additions rider and a minimized base premium. Term insurance has no cash value, and a policy sold for maximum death benefit builds cash value too slowly.
How much cash value is available in the first year?
About 70% to 93% of the first year's premium, depending on carrier and design, according to our 2026 carrier guide. Total cash value typically catches total premiums paid around year 5 or later for a healthy person.
How soon can you borrow against the policy?
Depending on carrier, a first loan is usually available about 10 to 45 days after funding, according to our 2026 carrier guide. The amount is limited to a share of the cash value, which is still below premiums paid in the early years.
What is direct versus non-direct recognition?
At a non-direct recognition carrier, such as MassMutual or New York Life, the dividend is the same on borrowed and unborrowed cash value. At a direct recognition carrier, such as Penn Mutual or Guardian, the dividend on the borrowed portion is adjusted while the loan is out.
Is the growth in an infinite banking policy tax-free?
Not unconditionally. Cash value grows tax-deferred, and loans from a policy that is not a modified endowment contract are generally not taxable while it stays in force (IRC 72(e)). A lapse or surrender with a loan outstanding can make the gain above your basis taxable as ordinary income.
What return does an infinite banking policy earn?
High cash value designs typically project about 3.5% to 5.3% a year over the long term, assuming current dividend scales hold. The carrier's dividend interest rate is a different, higher number and is not your return.
Who is infinite banking for?
Business owners, real estate investors and high-income earners who can fund a policy for 10 years or more and already have uses for capital that earn more than the loan cost. It is not a fix for high-interest debt or a place for money you need within a few years.
What is The And Asset?
The And Asset is BetterWealth's framework for using a properly structured whole life policy as a capital base. You only borrow against it for an activity that produces a return greater than the carrier's loan cost, so your dollars do two jobs at once: the policy keeps compounding, net of mortality and expense charges, while the deployed capital earns its own return.
How is The And Asset different from infinite banking?
IBC, as it is commonly marketed, says use the policy as a personal bank for any purchase. The And Asset says the policy is the capital base, the value comes from what the borrowed capital is deployed into, and you do not borrow if the deployment cannot beat the carrier's loan cost. It shares roots with Nash's concept but operates on different principles.
- Nelson Nash, Becoming Your Own Banker, the origin of the infinite banking concept.
- BetterWealth, The Ultimate 2026 IBC Carrier Comparison Guide: year-one cash value ranges, projected IRR ranges, 2026 dividend interest rates and loan timing across nine carriers.
- BetterWealth carrier fact sheet and illustration guidelines: loan recognition by carrier (Penn Mutual's 0.65% spread, Guardian's fixed 5% loan rate for 10 years) and break-even at year 5 or later.
- IRC Section 72 (Cornell Law): tax treatment of policy loans and amounts received, including 72(e) and 72(v).
- IRC Section 7702 (Cornell Law): the definition of a life insurance contract for tax purposes.
- IRC Section 7702A (Cornell Law): the 7-pay test and modified endowment contract status.
- BetterWealth, The Infinite Banking Concept Made Simple (with Illustrations), BetterWealth on YouTube, December 30, 2022.
- BetterWealth call, October 2026, client details removed: the investor case in section 06 and the carrier comparison in section 05.
- BetterWealth resources: The And Asset book, The And Asset YouTube channel, and the BetterWealth YouTube channel.
An honest look at whether infinite banking fits you.
On a discovery call, we look at your cash flow and your uses for capital, and tell you whether a policy belongs in your plan and how it should be designed, or that it does not. If you would rather learn first, The And Asset and BetterWealth YouTube channels go deep on the math.
Book a Discovery CallFind out what your policy is really doing.
If you were sold a policy for infinite banking, get a free review of it and an honest read on whether it is built to do the job.
Get a Free Policy ReviewFor a quick read first, try our Policy Grader.
I founded BetterWealth to treat life insurance as the wealth and capital tool it actually is, not the product most people get sold. I wrote The And Asset and host the BetterWealth and The And Asset YouTube channels. If you already own a policy sold as infinite banking, get a free policy review.