Whole life insurance is not worth it as an investment for most people: a well-designed policy projects a long-term return of about 4.0% to 5.3%, a return for safe money, not for beating the market. It is worth it for business owners and investors who need permanent coverage, will fund it for 10 years or more (our rule of thumb), and will use the cash value as a capital base, borrowing only when the use beats the carrier's loan cost.
Is whole life insurance worth it? For most people shopping for the best return on a dollar, no, and we will show you why with real numbers. For a narrower group, people who need coverage that never expires and who want a safe, accessible pool of capital they can borrow against while it keeps growing, it can be a competitive place to hold safe money, as the 35-year illustration below shows. The answer flips depending on which of three questions you are really asking: is it worth it as insurance, as an investment, or as a capital tool?
Whole life is a legal contract that does what the policy says, and it is frequently sold to the wrong people for the wrong reasons. Both halves of that sentence are true. The critics are right about the second half, so we give them their due first.
- "Is whole life worth it" is really three questions: worth it as insurance, as an investment, and as a capital tool.
- As an investment competing with stocks, whole life loses. Projected long-term returns typically run 4.0% to 5.3% on high cash value designs.
- As a safe, accessible place to hold cash, it compares well: in Todd Langford's 35-year illustration, a taxable account needed 5.16% a year to match a policy returning 4.03%.
- Early years are the cost: break-even against total premiums paid comes around year 5 or later, and cash value runs behind a simple savings account for years.
- It is not worth it for a temporary need, money you need within a few years, or anyone with no use for borrowed capital.
- Under The And Asset, you borrow only when deployed capital beats the carrier's loan cost.
01 / The real problemWhy is "is it worth it" the wrong question on its own?
Because the answer depends on the job you want the policy to do. A hammer is worth it for a nail and worthless for a screw. Whole life gets judged as a do-everything product because it is often sold as one, and it is not.
The problem worth solving for most business owners and investors is not beating the market. It is that their capital is always spoken for. When an opportunity shows up, getting money means selling something, paying tax, or asking a lender who can say no or freeze the line at the worst moment. The usual advice is to keep cash on the side, which has its own cost: idle capital. Whether whole life is worth it for you comes down to whether it solves that tension, between cash you can reach and growth you do not want to interrupt, better than the alternatives.
The internet argues about whole life as an investment because that is the easiest version to win or lose. The version that matters, control of capital, rarely gets an honest hearing.
02 / As insuranceIs whole life insurance worth it as insurance?
Only if your need for a death benefit is permanent. This is the cleanest of the three answers, and the one agents skip fastest because it rules out the most buyers.
Term insurance covers a temporary need: income during working years, a mortgage, children who will grow up. As Bobby Samuelson put it in our masterclass, term is cheaper "because it doesn't pay very many claims." If your need ends, term is the right tool.
The catch is what happens when the term ends and the need has not. In the illustration Todd Langford walked through in our whole life masterclass, a $1 million 30-year level term policy cost $1,820 a year. In year 31 the premium jumped to $36,000. Bobby Samuelson made the same point in that video from the carrier's side: term is "a loss leader," and carriers make their money when people who still need coverage reach the end of the term.
A permanent need looks different: an estate that will owe tax, a dependent who will never be independent, a business that needs cash at an owner's death, or a plan to pass capital to the next generation with certainty. Term ends before those needs do. Whole life covers them for as long as the policy is kept in force.
If your need is temporary, buy term. We mean it.
03 / As an investmentIs whole life insurance a good investment?
Not if a good investment means the highest return. High cash value designs at the nine carriers in our 2026 comparison guide typically project a long-term internal rate of return of 4.0% to 5.3% over 15 to 30 years, and those projections assume today's dividend scales hold, which the guide itself calls unlikely. That is a return for safe money, not a market-beating one. Anyone selling you a policy as a stock market substitute is misleading you.
Three corrections clear up most of the confusion.
The dividend rate is not your return. Carriers declared 2026 dividend interest rates from 5.1% (Ameritas) to 6.6% (MassMutual), according to the same guide. Cash value grows at the dividend net of mortality and expense charges, which is lower, and dividends are declared each year and not guaranteed. We walk through that mechanism in how whole life insurance cash value works.
The early years are the cost. Even a design built for cash value puts only 70% to 93% of the first year's premium into cash value in year one. Total cash value catches total premiums paid around year 5 or later for a healthy person. An illustration that shows break-even in year one or two deserves suspicion.
The fair comparison is cash, not stocks. Todd Langford, walking through his calculator in our masterclass, puts it plainly: a policy is "a savings vehicle, not an investment vehicle." So compare it with where your safe money sits now.
What does a real 35-year illustration show?
In our masterclass video, Todd ran a policy with a $27,184 annual premium for 35 years. The projected cash value at the end was about $2.09 million, and the death benefit started a little over $1 million and grew to about $3.3 million. The internal rate of return on that cash value was 4.03%. The $2.09 million and $3.3 million are not guaranteed: they are projections on the carrier's current dividend scale. Here is what an alternative account would have needed to earn every year to end with the same cash:
| Alternative account | Yearly return needed to match the policy (cash value, plus death benefit where term is added) |
|---|---|
| Tax-free, no fees | 4.03% |
| Taxed at a 22% bracket | 5.16% |
| Taxed, plus paying for $1 million of term (dropped at 64) | 5.55% |
| Taxed, plus term, plus a 1.5% management fee | 7.62% |
Now the honest other side, from the same illustration. Against a taxable savings account earning 2% with term insurance bought alongside it, the savings account was ahead of the policy for about 11 years, and in year five the policy trailed by about a premium and a quarter. After that the policy pulled ahead; by the end of the illustration, Todd showed about "$900,000 more" on the policy side, plus a death benefit that did not expire. That is the trade in one picture: years of lag in exchange for a better long-run result on safe money. It is figures from one illustration of one product, not a promise, and a policy designed differently will show different numbers.
If your only goal is the highest return on a dollar, buy index funds. Whole life is competing with your cash, not your stocks.
04 / The criticsIs whole life insurance a scam, and why do so many people say it is not worth it?
No, whole life is not a scam: it is a legal contract that does what the policy says. It is often oversold, though, and the critics are describing real policies. The White Coat Investor, one of the top results for this question, calls whole life "designed to be sold, not bought" and points to first-year agent commissions of 50% to 110% of the first year's premium. Reddit, also in the top results, makes the same case. A policy dropped in its early years is dropped in exactly the stretch where, as shown above, cash value trails premiums until around year 5 or later and can trail a plain savings account for longer.
We agree with more of that than you might expect. Three pitches deserve every bit of skepticism they get:
- "It earns market returns." It does not. See the 4.0% to 5.3% range above.
- "You pay yourself interest on a policy loan." You do not. Loan interest goes to the carrier.
- "It works for any purchase." It does not. Borrowing only makes sense when the deployed capital beats the carrier's loan cost.
Two points the critics usually leave out. First, on commissions, Bobby Samuelson noted in our masterclass that term often pays a higher commission rate as a percentage of premium; whole life pays more dollars only because its premium is larger. Second, most bad outcomes come from design and fit, not from the contract itself: a policy built for the largest death benefit, sold to someone who wanted accessible cash, and dropped in the expensive early years.
The product is honest. The pitch often is not.
05 / As a capital toolWhat does it mean to use whole life as a capital tool?
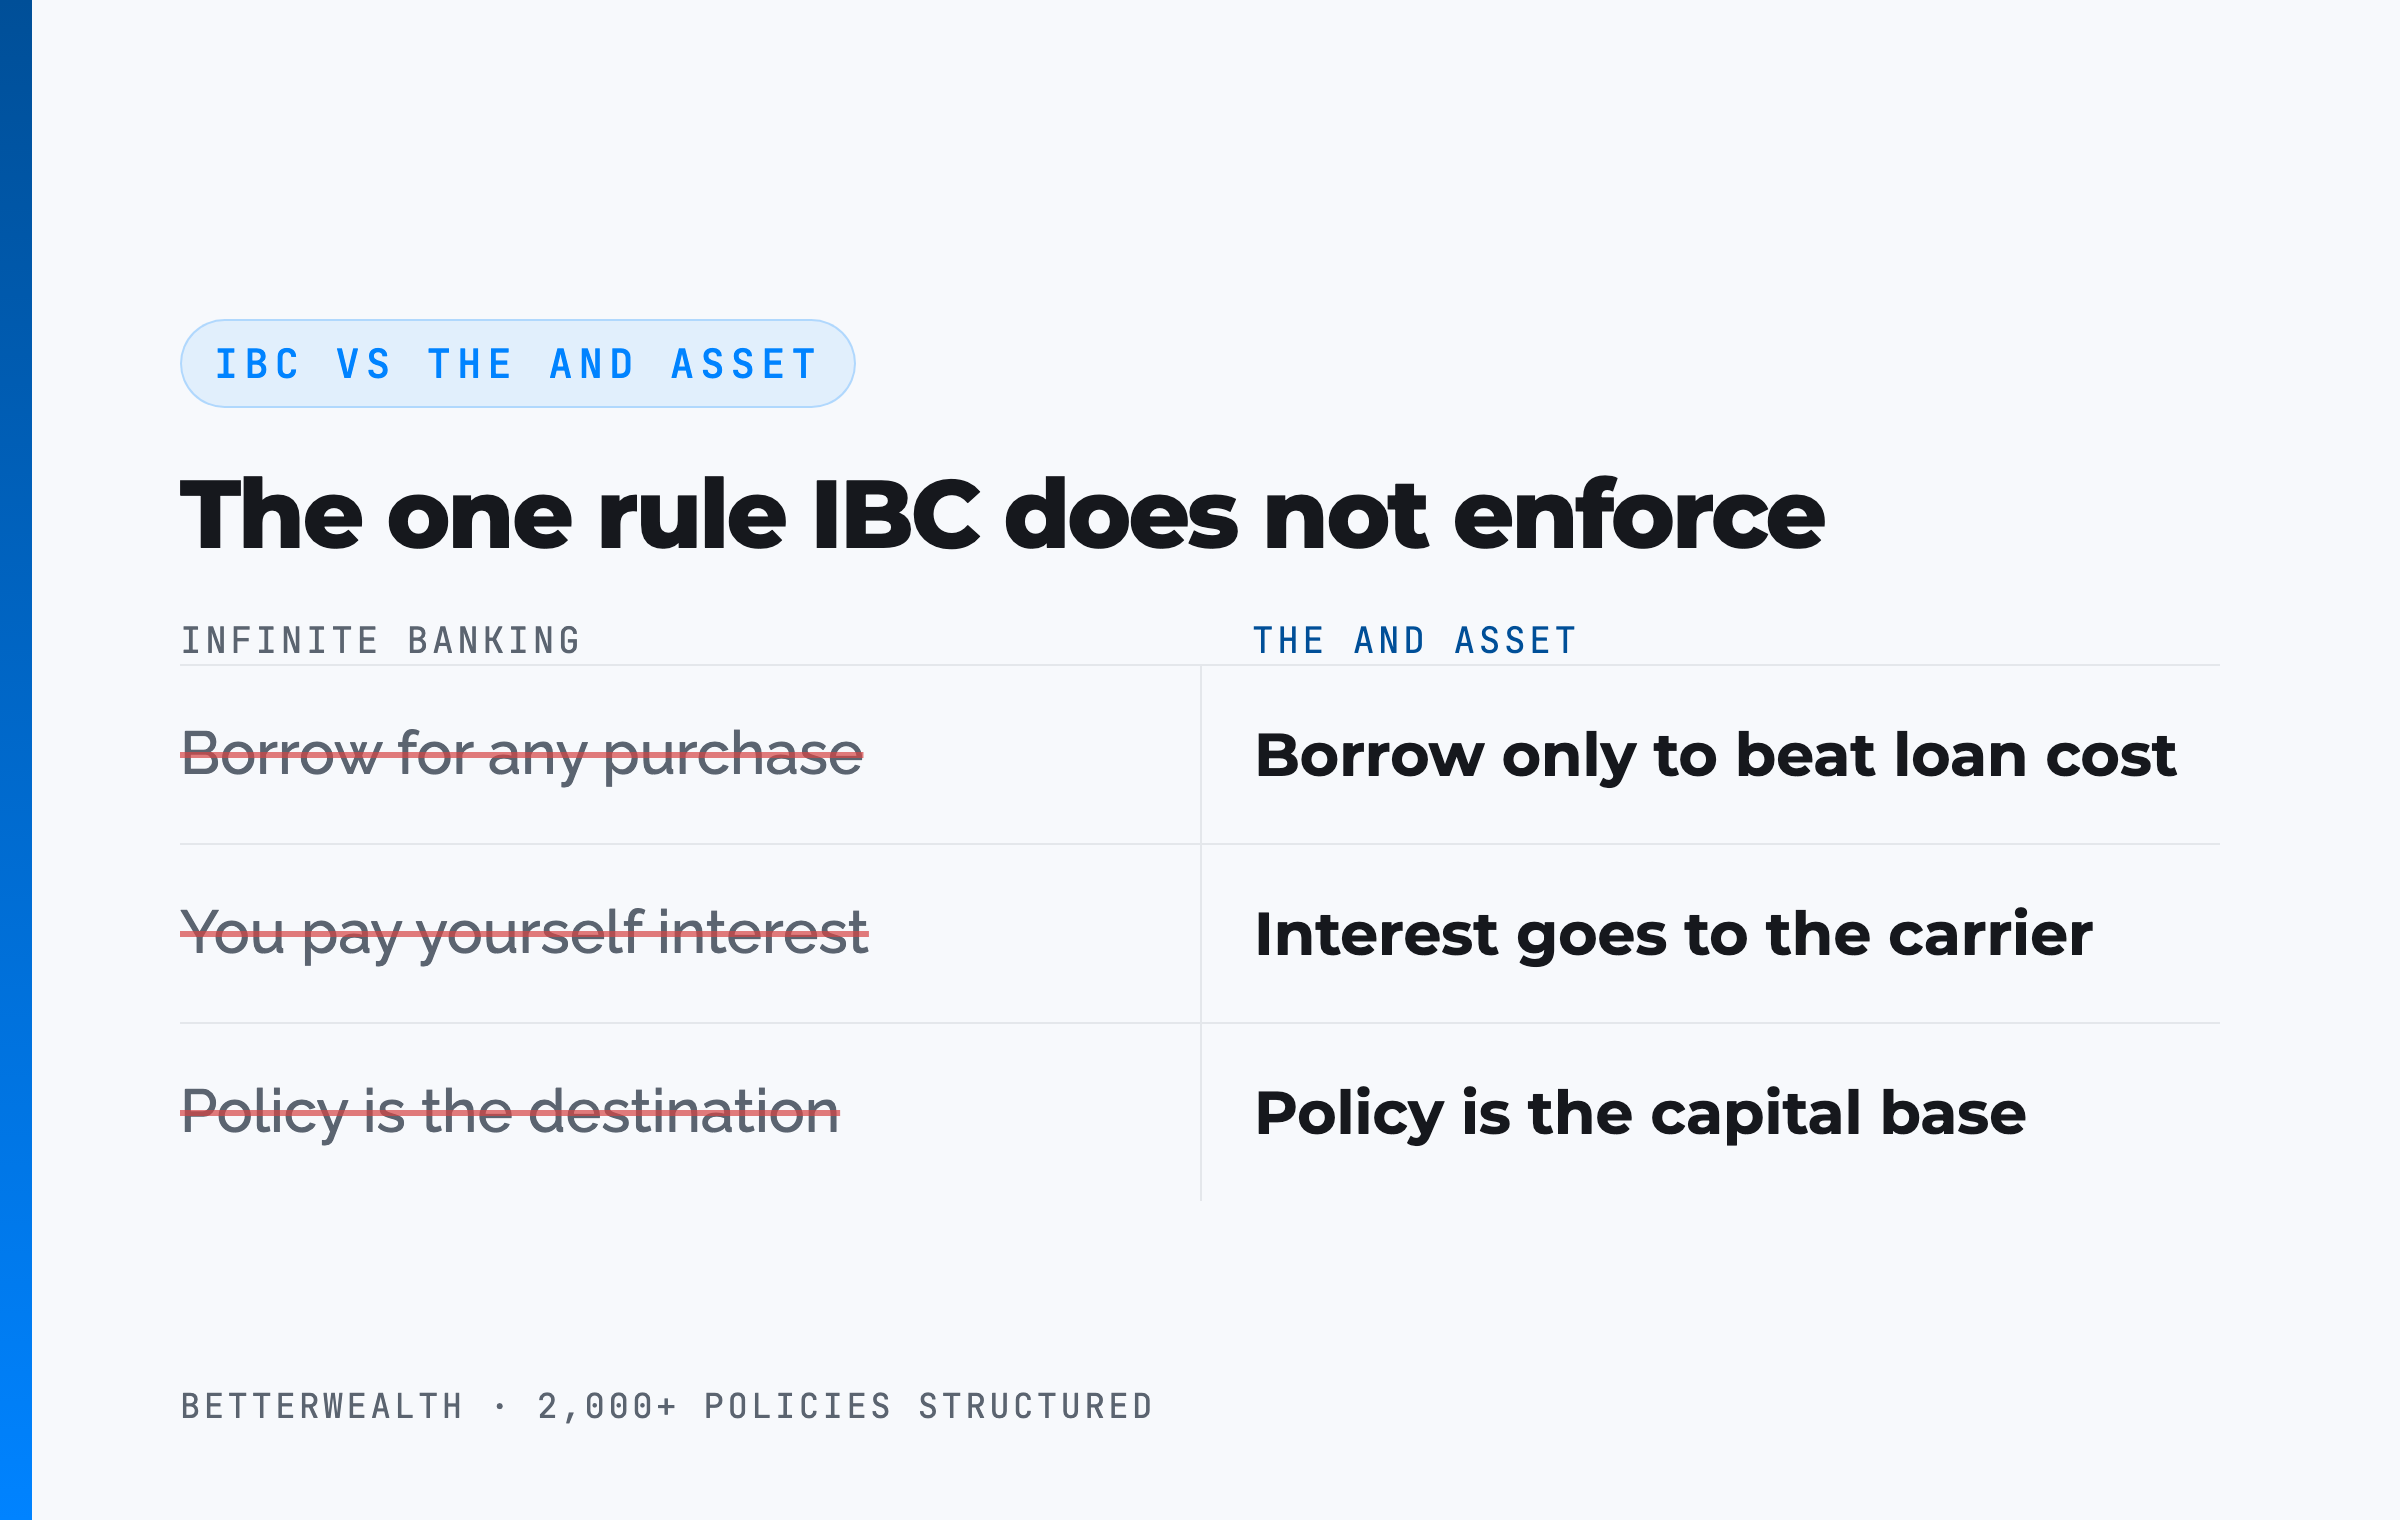
It means treating the policy as a base of capital you can borrow against while it keeps compounding, rather than as an investment you are trying to beat the market with. This is where the answer can move from "not worth it" to "worth it" for the right person, and it is where BetterWealth's framework, The And Asset, lives.
Nelson Nash introduced the idea of using whole life as a personal banking system in Becoming Your Own Banker. His core insight holds: you either pay interest to outside lenders or give up what your idle cash could have earned. The And Asset shares those roots but operates on different principles.
Where infinite banking ends and The And Asset begins
IBC, as it is commonly marketed, says use the policy as a personal bank for any purchase. The And Asset says the policy is the capital base, and you borrow only when the deployed dollars out-earn the carrier's loan cost, because a loan that does not clear that cost leaves you paying the carrier more than the capital earns. Meanwhile the cash value keeps compounding, net of mortality and expense charges. Your dollars do two jobs: the policy earns its return, and the deployed capital earns its own. That is the AND.
One dollar. Two jobs. That is the test.
Whole life is worth it for a specific person doing specific things.
It is worth it if
- You have a permanent insurance need
- You can fund it for 10+ years
- You can name a use for capital that beats the loan cost
- You value control and tax treatment over maximum yield
It is not worth it if
- Your insurance need is temporary
- You may need the money within a few years
- You want a stock market alternative
- You cannot deploy borrowed capital productively
If you are in the first column, a discovery call will tell you whether a policy belongs in your plan and how it should be designed. If you are in the second, we will tell you that too.
Book a Discovery Call06 / The mathDoes the return clear the carrier's loan cost?
The capital-tool case holds only if what you deploy borrowed money into earns more than the carrier's loan cost. Loan rates differ by carrier and change with the rate environment, so get the current rate from the carrier and treat it as the hurdle.
The structure is simple. You borrow against the policy at the carrier's loan rate. The cash value keeps compounding, with the borrowed portion credited according to the carrier's method. Penn Mutual, for example, uses direct recognition, with a guaranteed 0.65% spread between the loan rate and the dividend rate in years 1 to 10, according to our 2026 carrier guide, and Guardian is direct recognition with a fixed 5% loan rate for the first 10 years; MassMutual and New York Life use non-direct recognition. The capital you deploy earns its own return. If that return beats the loan cost, you keep the spread. If it does not, you have borrowed money to lose money slowly.
A worked example, with an illustrative use: borrow $100,000 at Guardian's fixed 5% loan rate and the interest is $5,000 a year. Put the money into something that earns 9%, or $9,000 a year, and you keep a $4,000 spread before tax while the cash value keeps compounding under the carrier's crediting method. If the use earns 4%, you are $1,000 a year behind, and the right answer was not to borrow.
Two tax rules keep this honest. A loan from a policy that is not a modified endowment contract is generally not taxable income while the policy stays in force (IRC 72(e)). But if the policy lapses or is surrendered with a loan outstanding, the loan is generally treated as an amount received, and the amount by which the gross cash value (including the part used to pay off the loan) exceeds your basis (generally premiums paid, less tax-free amounts already received) is generally taxable as ordinary income. A policy funded past its 7-pay limit under IRC 7702A becomes a modified endowment contract: its loans are generally taxed gain-first, and the taxable part of a distribution before age 59½ can generally carry a 10% additional tax (IRC 72(v)). Check your own situation with a tax advisor.
If the deal does not clear the loan rate, do not borrow.
07 / When it is not worth itWhen is whole life insurance not worth it?
For more people than it is worth it for. These are not edge cases.
Your need is temporary. Term is cheaper and correct for a need that ends.
You may need the money within a few years. With cash value trailing premiums until around year 5 or later, a policy is a poor place for money you might need soon.
You cannot commit to funding it for a decade or more. The early costs are front-loaded and the benefits build late. Dropping a policy in year three locks in the worst part of the curve.
You want it to fix high-interest debt next month. It does not create cash you do not have, and the early-year lag makes a short-term liquidity problem worse.
You have no use for borrowed capital and no permanent need. Then you do not need the capital base, and there are cheaper ways to hold cash.
If whole life is wrong for your situation, the right answer is no, and we would rather say it than sell you something you will resent in three years.
Free whole life resources and education.
The And Asset Vault is where we keep free whole life insurance resources and education, for anyone who wants to learn more before deciding whether a policy is worth it.
Open the Vault08 / Already own oneIs the whole life policy I already own worth keeping?
That is a question about your policy, not whole life in general. It depends on how the policy was designed and how far past the early-cost years it is, and sometimes the honest answer is "keep it." One prospect on a recent strategy call asked us almost exactly this: whether it was "worth it to ... max fund" a policy already owned and use it as "a family bank." The policy was an indexed universal life policy, not whole life, but the review works the same way.
One of our coaches had looked at the max-funded illustrations and gave a straight answer: "it's a solid policy." The surrender charges ran until year 11, but they came "pretty close in line with the accumulation value over the 3, four, five year mark." The lead coach agreed, "it's not a bad policy," and gave a rule of thumb for that indexed policy: "fund it for at least 20 years" and "max fund it for at least 10." The prospect already knew not to borrow against it for "depreciating assets" like cars. The And Asset test goes one step further: borrow against it only when the use beats the carrier's loan cost.
If you own a policy and wonder whether it was worth it, start with three questions: what was it designed to do, how far through the early-cost years is it, and what would surrendering it cost you now, including tax on any gain and any outstanding loan.
The policy that trailed a 2% savings account for 11 years, then pulled ahead
Todd's example policy carried a $27,184 annual premium over 35 years. It projected an internal rate of return of 4.03% on its cash value, with negative annual returns in the early years and higher ones later. Against a taxable 2% savings account plus term coverage, the savings account led for about 11 years.
Todd's own caution matters: these projections use the current dividend scale, and he noted policies bought 30 years ago saw dividends "in the 9 plus range," while today is "probably the lowest dividend time we've ever seen." Judge any illustration you are shown by its assumptions, not its last line.
The lag is real. So is what comes after it, if you keep the policy long enough.
09 / DecideHow do you decide if whole life insurance is worth it for you?
- Name the job. Permanent death benefit, a safe place for cash you want to reach, a capital base to borrow against, or a mix. If you cannot name one, stop here.
- Check the need's length. If it ends in 20 or 30 years, price term first.
- Check your horizon. Can you fund the policy for 10 years or more without needing the money? If not, wait.
- Ask for the design before the premium. How much of the premium goes to base, paid-up additions and term? When does cash value pass total premiums paid? Expect year 5 or later.
- Compare with your real alternative. Put the policy's projected return next to where your safe money sits now, after tax, as in the table in section 03.
What does the design change?
The split between base premium and paid-up additions (PUA), written base/PUA, drives early cash value. A heavier base share raises the required base premium and slows early cash value; a heavier PUA share does the opposite, up to the MEC limit. In our post on converting term to whole life, a 50/50 design required more than $24,000 of base premium, against about $9,900 on a 20/80 design, and the higher base is what dragged early cash value. Flexibility matters too: our 2026 carrier guide calls Ameritas ideal for 40/60 designs with "room to grow," because it allows paying up to 100% more PUA than illustrated as long as the policy stays under the MEC limit.
10 / ComparisonHow does whole life compare with the alternatives?
A well-designed whole life policy trades early liquidity and raw return for control, tax treatment and uninterrupted compounding while borrowed against. Here it is next to the tools business owners and investors actually use.
| Dimension | Whole Life (used as a capital base) | Term + Invest | HELOC | Taxable Brokerage |
|---|---|---|---|---|
| Raw return | About 4.0% to 5.3% projected long-term, net of internal costs | Higher long-run, market-dependent | None (a credit line, not an asset) | Higher long-run, taxed on gains |
| Liquidity | Loans against cash value; 70% to 93% of first-year premium in year one | Depends on the investments | Fast once approved, but can be frozen or reduced | Liquid, settles in days |
| Tax treatment | Loans generally not taxable while in force and not a MEC (IRC 72(e)) | Depends on account type | Deductibility rules are narrow and depend on how the money is used; verify with a tax advisor | Gains and dividends taxed |
| Control | Borrow up to the carrier's limit on cash value at the carrier's rate; you set repayment; keeps compounding while borrowed, credited per the carrier's direct or non-direct recognition method | Full control of investments | Lender sets terms and can revoke access | Full control, no built-in borrowing |
Raw return. Term plus investing and a brokerage account both beat whole life on raw return. Whole life is bought for the other three rows.
Liquidity and control. A HELOC is a line the lender can freeze or cut. A policy loan is limited to a share of the cash value and priced by the carrier, but it is not a credit line a bank can cut, though an unpaid loan that grows past the cash value can cause a lapse.
Tax and compounding. A non-MEC policy loan is generally not taxable while the policy is in force, and the cash value keeps compounding while you borrow. No credit line does that, because a credit line is not an asset.
An honest conversation about whether this is worth it for you.
On a discovery call, we look at your situation and tell you whether whole life belongs in your plan, and when it does not. If you would rather learn first, The And Asset and BetterWealth YouTube channels go deep on the math.
Book a Discovery CallWatch Todd Langford's illustration and Bobby Samuelson's term versus permanent breakdown in our whole life masterclass.
FAQIs whole life insurance worth it: common questions
Is whole life insurance worth it?
Not as an investment for most people, since well-designed policies project about 4.0% to 5.3% over 15 to 30 years. It can be worth it for business owners and investors who need permanent coverage, will fund it for 10 years or more, and will borrow against it only when the use beats the carrier's loan cost.
Is whole life insurance a good investment?
Not compared with stocks. Its value is as a safe, accessible place for cash: in Todd Langford's 35-year illustration, a policy returning 4.03% matched a taxable account earning 5.16% a year at a 22% bracket, and it also carried a death benefit.
Is whole life insurance a scam?
No, but it is often oversold. The contract does what the policy says. The problems are pitches that promise market returns, claim you pay yourself interest on loans, or sell it to people with no permanent need and no use for the cash.
When is whole life insurance not worth it?
When your need is temporary, when you may need the money within a few years, when you cannot fund it for a decade or more, when you want it to fix debt quickly, or when you have no permanent need and no use for borrowed capital.
How long until whole life insurance pays off?
Total cash value typically catches total premiums paid around year 5 or later for a healthy person in a maximum cash value design. Against a taxable 2% savings account plus term, Todd Langford's illustration showed the policy behind for about 11 years before pulling ahead.
Why does whole life have low cash value in the early years?
The early premiums pay for insurance costs and policy expenses before compounding builds. Even designs built for cash value put 70% to 93% of the first year's premium into cash value in year one, so break-even comes around year 5 or later.
Is whole life better than term and invest the difference?
On pure investment return, term and invest usually wins. Whole life competes on permanent coverage, a safe and accessible cash base, and borrowing without selling the asset. Term also gets expensive if you still need coverage after it ends: in one illustration a $1 million 30-year term went from $1,820 to $36,000 a year in year 31.
Does the cash value grow at the dividend rate?
No. The dividend interest rate is a gross figure; 2026 rates ran from 5.1% to 6.6% across nine carriers. Cash value grows at the dividend net of mortality and expense charges, and dividends are declared each year and not guaranteed.
Are whole life policy loans taxable?
Generally not while the policy stays in force and is not a modified endowment contract (IRC 72(e)). If the policy lapses or is surrendered with a loan outstanding, the amount by which the gross cash value (including the part used to pay off the loan) exceeds your basis (generally premiums paid, less tax-free amounts already received) is generally taxable as ordinary income.
Is the whole life policy I already own worth keeping?
It depends on how it was designed and how far past the early-cost years it is. Surrendering early locks in the worst part of the curve and can create tax on any gain. A free policy review will show what your policy is doing and whether it fits what you bought it for.
What is The And Asset?
The And Asset is BetterWealth's framework for using a properly structured whole life policy as a capital base. You only borrow against it for an activity that produces a return greater than the carrier's loan cost, so your dollars do two jobs at once: the policy keeps compounding, net of mortality and expense charges, while the deployed capital earns its own return.
How is The And Asset different from infinite banking?
IBC, as it is commonly marketed, says use the policy as a personal bank for any purchase. The And Asset says the policy is the capital base, the value comes from what the borrowed capital is deployed into, and you do not borrow if the deployment cannot beat the carrier's loan cost. It shares roots with Nash's concept but operates on different principles.
- BetterWealth, If You Only Watch One Whole Life Insurance Video, Make It This, BetterWealth on YouTube, October 19, 2026: Todd Langford's 35-year illustration (chapter at 42:42) and Bobby Samuelson on term versus permanent coverage and commissions (chapter at 0:59).
- BetterWealth, The Ultimate 2026 IBC Carrier Comparison Guide: year-one cash value ranges, projected IRR ranges and 2026 dividend interest rates across nine carriers.
- IRC Section 72 (Cornell Law): tax treatment of policy loans and amounts received from life insurance contracts, including 72(e).
- IRC Section 7702 (Cornell Law): the definition of a life insurance contract for tax purposes.
- IRC Section 7702A (Cornell Law): the 7-pay test and modified endowment contract status.
- The White Coat Investor, Is Whole Life Insurance Worth It?: the critic's case, including first-year commission ranges.
- Nelson Nash, Becoming Your Own Banker, the origin of the infinite banking concept.
- BetterWealth strategy call, November 2026, prospect details removed: the max-funded policy review in section 08.
- BetterWealth, Convert Term to Whole Life Insurance: Best Companies: the 50/50 versus 20/80 base premium comparison.
- BetterWealth illustration guidelines: break-even at year 5 or later for healthy individuals, and carrier loan structures (Guardian's fixed 5% loan rate for 10 years; MassMutual and New York Life non-direct recognition).
Find out if yours is worth keeping.
Get a free review of the permanent life insurance policy you already own, and an honest read on whether it is worth keeping.
Get a Free Policy ReviewFor a quick read first, try our Policy Grader.
I founded BetterWealth to treat life insurance as the wealth and capital tool it actually is, not the product most people get sold. I wrote The And Asset and host the BetterWealth and The And Asset YouTube channels. If you already own a policy and want to know whether it is worth keeping, get a free policy review.